Capsule House Currency Cost in Cross-Border Orders
Capsule house currency cost: denomination, what the quoted amount excludes, transfer and credit charges, hedging in plain terms and the clause to write.
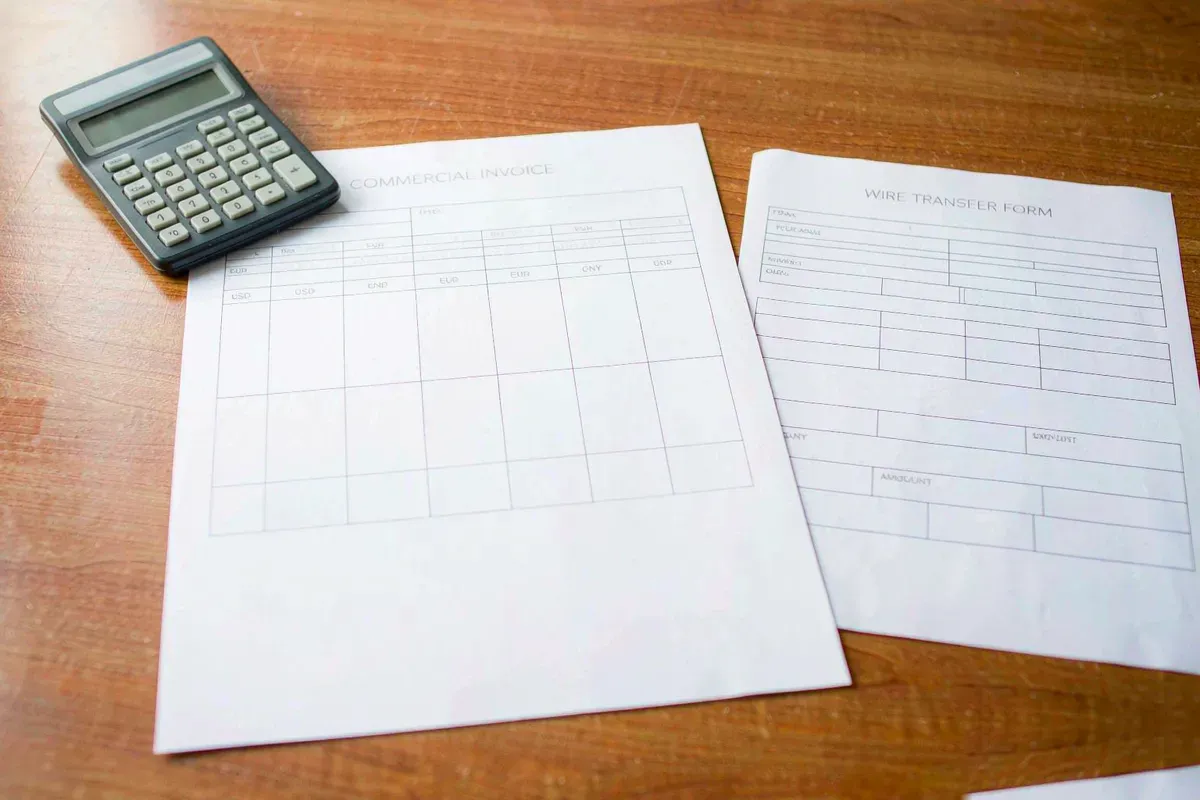
On a cross-border capsule order the price is only one of the money decisions. The other three — which currency the price is written in, who carries the movement between deposit and balance, and which payment instrument is used — decide what actually leaves the buyer's account, and they are usually agreed last and most casually. This page separates those decisions, explains what each one costs and where the cost lands, and sets out the clause wording worth agreeing before the order is signed. Payment timing and instalments is a separate subject covered elsewhere; quantity pricing is in capsule house bulk order pricing, the negotiation side is in capsule house price negotiation, and the general commercial reference is capsule house price and the capsule home cost guide.
Which currency the price is written in
The first decision is denomination, and it is a risk-allocation decision rather than an administrative one. In practice three patterns appear:
- Supplier's domestic currency. The supplier carries no conversion risk, so the price usually reflects that. The buyer carries the movement for the whole period between agreeing the price and paying the balance.
- A major trading currency. Common in export trade. The supplier may still have an internal conversion, and the buyer's exposure depends on their own currency's movement against it.
- Buyer's currency. Convenient for the buyer's internal approval, but the supplier is quoting a rate they have to live with for months, which tends to be reflected in the number.
The relevant question is not which pattern is better in the abstract. It is how long the exposure lasts. A price agreed in one month and paid in the next is a different proposition from a deposit today and a balance in nine months, and the longer the gap the more the denomination matters.
What the quoted amount does and does not include
A quoted amount and the amount debited from the buyer's account are rarely the same figure. The difference is not an error; it is a set of charges applied by intermediaries:
- Telegraphic transfer charges. Applied by the sending bank and often by intermediary and receiving banks as well, so the receiving party may see less than the invoice figure.
- The exchange rate applied. Not a published mid-market rate but a rate the bank applies, which includes a spread.
- Any lifting or handling fee applied by an intermediary bank in a third country.
- Documentary credit charges. Where a letter of credit is used, there are charges for issuance, advising, amendment and examination, and these are often higher than a simple transfer.
The practical rule: state in the contract which party bears which charges. Without that sentence, the outcome depends on bank practice rather than on the agreement, and the shortfall arrives as a reconciliation problem weeks later.
Choosing the instrument
| Instrument | What it gives the buyer | What it costs |
|---|---|---|
| Telegraphic transfer | Simple, fast, familiar | Low charges; little control once sent |
| Documentary credit | Payment against defined documents | Higher charges; document discipline on both sides |
| Escrow or staged release | Funds released against agreed evidence | Administration and fees; needs clear milestones |
| Open account | Cash flow advantage | Counterparty exposure; usually only after a relationship exists |
The choice is usually driven by order size and by whether the two parties have traded before. A first order of any size justifies a more controlled instrument despite the cost, because the cost of a documentary credit is small compared with the amount at risk, while the cost of a failed first transaction is not. No fee figures are quoted here; obtain the actual tariff from your bank.
Hedging, in plain terms
If the buyer's currency and the price currency differ, the exposure can be left open or managed. The management options are products offered by banks — a forward contract that fixes a rate for a future date, or an option that sets a worst case while leaving upside. Which is appropriate depends on the size of the exposure, the certainty of the payment date and the buyer's own treasury policy, and it should be discussed with the buyer's bank rather than decided from an article.
Two practical points are worth making regardless. The first is that hedging needs a reasonably firm payment date, which is why the milestone schedule matters to the treasury function and not only to the project team. The second is that hedging a payment that may not happen creates its own exposure, so the order should be firm before the hedge is placed.
Milestones spread the exposure as well as the cash
A deposit plus a balance is the simplest structure; a deposit, a pre-shipment payment and a balance after arrival is more common on larger orders. Milestones change the currency exposure as well as the cash flow, because each payment is converted on its own date at its own rate. The consequence worth planning for:
- The total paid in the buyer's currency is not known in advance unless it is hedged or the price is fixed in that currency.
- More milestones mean more conversion events and more charges, so there is a point at which additional stages cost more than they save.
- A milestone tied to a physical event — production complete, vessel loaded, arrived — can move, and a moved milestone moves the payment date and therefore the rate.
Refunds, changes and the awkward cases
Three situations produce friction, and all three are easier if they are written down first:
- An order changed after deposit. Which currency the adjustment is calculated in, and at which rate.
- A refund. Whether it is the amount received or the amount invoiced, who bears the conversion difference, and how long it takes.
- A disputed balance. Whether the undrawn portion of a documentary credit can expire while the dispute is open, and what happens then.
The clause worth writing
A short, clear currency and payment clause does more than any other document on this list. It should state: the currency of the price; how long that price is valid; which party bears which bank charges; which instrument is used and who pays for it; the milestone events and what evidence triggers each; and what happens on a refund or a change. Keep it short enough that both sides actually read it. If the wording matters commercially, have it reviewed by your own adviser rather than copied. Requirements may vary by application, market and applicable standard.
Where the treasury conversation belongs
On most projects the payment schedule is agreed by the commercial team and the currency exposure is discovered later by the finance team. Bringing finance in before the order is signed costs an hour and usually changes two things: the choice of instrument, and the number of milestones. Fewer, larger payments reduce the number of conversion events and the charges attached to them, while more milestones improve control over delivery. The right balance depends on the relationship with the supplier and on the size of the order, and it is easier to set deliberately than to renegotiate later.
More from the Blog

Capsule Home Cost Guide: What You Really Pay in 2026
EXW, shipping, install and the hidden line items — a transparent breakdown of total landed cost.
Read article →
How to Install a Capsule Home in 3 Days: A Step-by-Step Guide
From site prep to first guest — the exact sequence our install crews follow on every deployment.
Read article →
Real Owners, Real Numbers: Success Stories
How a lakeside resort, a Spanish glamping site and a Singapore dealer hit their targets.
Read stories →Talk to the Factory
Ready to Ride the 2026 Wave?
Get the latest catalog, pricing tiers and a layout sketch for your land — straight from the engineering team.